On the environmental impact of artificial intelligence, video games, and social media in 2025
Study objective
This work compares, using the best evidence available in 2025, the order of magnitude of the annual environmental impact of three mass digital markets—artificial intelligence, video games, and social media—and discusses whether the dominant question in public discourse regarding digital sustainability ('which market pollutes the most?') is appropriately framed.
The hypothesis guiding this research is that it is not. The question conflates two ontologically distinct magnitudes—intensity per unit of use and aggregate by market scale—and shifts ethical responsibility toward individual consumption when available data indicate that the decisive lever lies elsewhere: in infrastructure, product design, and regulatory frameworks.
The study does not seek to issue a verdict on which of the three markets is 'the worst'. It seeks something prior: to clarify what is being measured when comparisons are made, the level of confidence in the available data, and the ethical consequences derived from the asymmetry between these markets.
1. Why the public conversation is misdirected
In 2025, the conversation surrounding digital sustainability has focused heavily on artificial intelligence. There are material justifications for this: it is the sector with the highest intensity per unit of compute, the fastest growth in electricity consumption within data centres, and the most robust primary evidence. The International Energy Agency maintains that AI will be the primary driver of data centre electricity growth throughout this decade, with scenarios projecting up to 945 TWh globally by 2030.
This concentration of the debate carries an analytical cost. While the discussion focused on whether a ChatGPT query consumes 'a bottle of water'—a simplified and poorly documented figure—two other mass digital ecosystems have continued to operate with unequal public scrutiny. One of them, social media, very likely exceeds AI in aggregate annual footprint of electricity, water, and emissions. This does not render AI a 'clean' market nor absolve its current deployments: it simply shifts the question.
An honest comparison requires distinguishing two factors that are routinely conflated in public discourse:
Environmental intensity per unit of use. The cost—in electricity, water, and emissions—of a specific hour, session, or query.
Aggregate annual impact by market scale. The total sum of the entire market at the end of the year, multiplying intensity by users and hours.
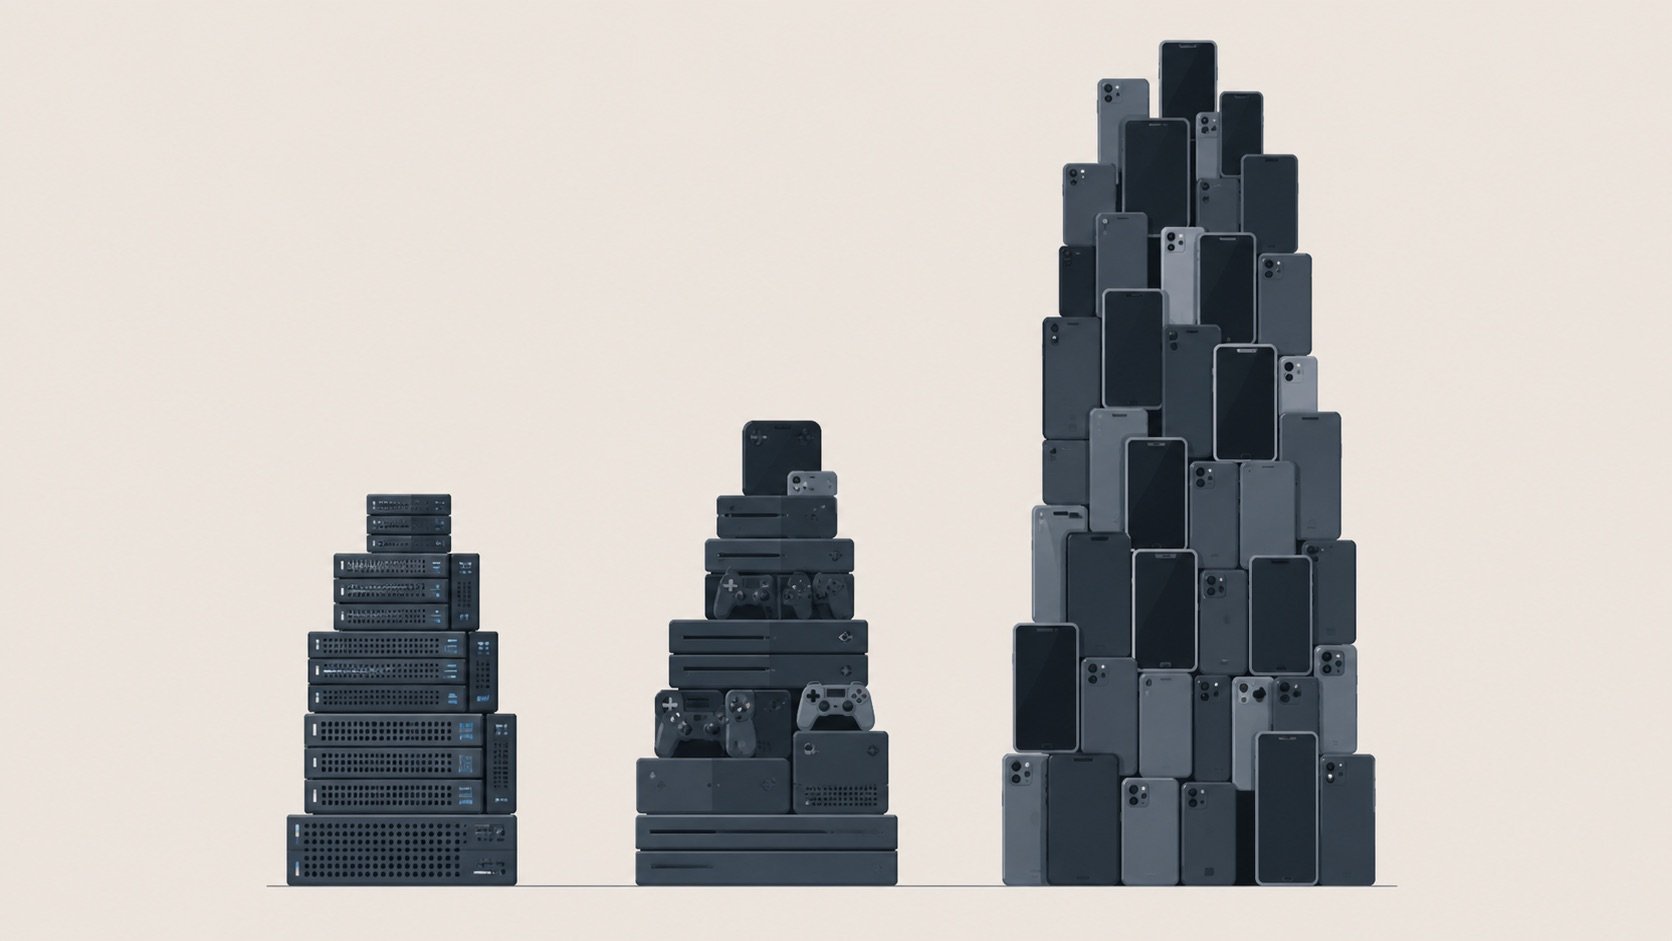
AI scores very high in intensity and still relatively low in aggregate, as its mass deployment is recent. Social media scores low in intensity per minute but very high in aggregate, as it totals 5.24 billion users and 894 hours of use per year for the average user. Video gaming remains in an intermediate position, with a relevant but technically more manageable footprint.
These three figures cannot be ranked in a 'league' without losing information. Each market possesses a distinct profile and, above all, a distinct consumption structure. That ontological difference is what renders the initial question poorly formulated and what opens the ethical problem addressed by this study.
2. Methodology and assumptions
The comparison works with three levels of evidence, explicitly prioritised.
The first category consists of direct 2025 estimates published by primary studies or reports. This primarily includes AI, thanks to recent work published in Patterns (Cell Press) that specifically estimates the global footprint of AI systems for 2025.
The second category consists of modelled sectoral estimates using market data and observed technical parameters, which are unaudited. This includes gaming and social media. For gaming, the starting point is the Lawrence Berkeley National Laboratory benchmark for the United States—34 TWh/year and 24 MtCO₂/year in 2019—which is cross-referenced with the 2025 market size, distribution by device type, and measured consumption on modern consoles. For social media, the starting point is the digital consumption analysis published in Nature Communications and the state of global usage collected by DataReportal, assigning the sector a band of 12-18% of the total digital footprint per user.
The third category involves proxies and indirect estimates where no primary sectoral data for 2025 exists. This applies to the majority of e-waste specifically attributable to each of the three markets, which is marked as 'unspecified' where no robust primary source is available.
This hierarchy matters. A mature public debate on digital sustainability cannot continue to treat an attributional estimate of medium-low confidence as if it were audited data. Methodological transparency is now an ethical issue, not merely a technical one.
When a study provides CO₂e but not sectoral TWh, this report applies a proxy conversion using a global average grid factor. When sectoral water data is missing, it models indirect water based on the water intensity of electricity supply. In both cases, the result must be read as an order of magnitude, not as an official inventory.
An additional, significant limitation is the asymmetry of system boundaries. AI is reasonably measurable as the operational footprint of specific systems. Video games and social media are ecosystems of mass digital consumption where user terminals, screens, networks, and, above all, usage time are critical factors. The 2025 GreenIT world study demonstrates that, within the global digital landscape, user equipment accounts for approximately 54% of global warming potential, compared to 23% for networks and 23% for data centres; in terms of total primary energy, the usage phase exceeds 80%. This explains why social media and video games can present high aggregate footprints without being as intensive per unit of compute as AI.
3. Artificial intelligence
AI is the only one of the three markets with a reasonably explicit global estimate for 2025. The cited Patterns article notes that the electrical demand of AI systems was approximately 9.4 GW at the end of 2024, with a projected increase to 23 GW during 2025. Converted to annual energy, the approximate range is 82 to 202 TWh. The same study estimates a footprint for 2025 of 32.6 to 79.7 MtCO₂e and 312.5 to 764.6 billion litres of water.
The IEA reinforces this diagnosis from a different perspective. Data centres consumed approximately 415 TWh globally in 2024, with AI serving as the primary driver of this growth. The agency’s baseline scenario projects 945 TWh by 2030, with centres optimised for AI quadrupling their electricity consumption by that time.
There are three dominant drivers. First, accelerated servers—GPUs and equivalent units—and their power density. Second, the associated infrastructure: cooling, uninterruptible power supply systems, and internal networks. Third, the local electricity mix: the physical electricity consumed today by data centres on a global scale still has a significant presence of coal and gas, although renewables and nuclear are gaining ground. The water footprint is mostly indirect—associated with electricity generation—rather than direct through cooling: the study published in Nature Sustainability on AI servers in the United States estimates that indirect water accounts for 71% of the total.
E-waste specifically attributable to AI in 2025 is not well defined. A paper in Nature Computational Science projects an accumulation of 1.2 to 5.0 million tonnes of electronic waste for generative AI between 2020 and 2030; subsequent work suggests that with longer server lifespans, the upper end may be moderated. The global annual mass of AI e-waste in 2025 remains unspecified in primary peer-reviewed evidence, although the trend is unequivocally upward and closely linked to the renewal of servers, accelerators, and HBM memory.
AI also possesses the best potential systemic benefit profile of the three markets: electrical grid optimisation, industrial predictive maintenance, materials discovery, and the acceleration of innovation in batteries and solar photovoltaics. There is real technical scope for mitigation: the cited Nature Sustainability study models that the combination of best practices in PUE and WUE, selective geographical location, advanced liquid cooling, and greater renewable penetration can reduce the residual carbon and water footprint by up to approximately 73% and 86% respectively by 2030 in the US.
Whether that potential materialises depends on governance, not technology.
4. Video Games
Video gaming lacks a consolidated and comparable global 2025 accounting. The most robust structural data remains the Lawrence Berkeley National Laboratory study for the United States, which estimated 34 TWh/year and 24 MtCO₂/year in 2019. Since then, the global market has grown substantially: Newzoo values the gaming market at 188.8 billion dollars in 2025, with 3.58 billion players, of whom approximately 3 billion play on mobile; mobile maintains around 55% of the sector's global expenditure.
Taking that benchmark as an anchor, correcting for the greater global weight of mobile, and adding PC, console, downloads, and a small fraction of cloud gaming, this study places the 2025 band at 110 to 190 TWh of electricity—centred around 145 TWh—, 48 to 84 MtCO₂e, and 170 to 670 billion litres of modelled indirect water. These are low-to-medium confidence figures, useful for order of magnitude.
The primary driver here is not data centres. It is user devices: consoles, gaming PCs, laptops, mobiles, screens, and peripherals over billions of hours of annual use. Microsoft publishes global average power baselines per game of 122 W for Xbox Series X and 61 W for Series S, an unusual level of transparency that allows studios to detect and correct “energy bugs” in their engines.
The sector is the only one of the three with a mature voluntary agreement and public data. The European Game Console Voluntary Agreement (GCVA) documents reductions of up to 50% in the energy consumption of certain UHD consoles within the same generation, driven by power limits and improvements in navigation, media, and standby modes. The mitigation lever in video games lies not only in hardware but also in software and default system settings.
Sectoral e-waste for 2025 remains unspecified. The material problem is concentrated in consoles, controllers, headphones, GPUs, PCs, and screens, and the most critical pressure is likely not the final waste but the demand for metals and minerals in short renewal cycles. The GreenIT study itself underscores that the depletion of minerals and metals is already an indicator as critical as, if not more so than, CO₂ in the digital sphere.
The benefit of video gaming for sustainability is more indirect than that of AI, but not null. There are three avenues: accounting standards and best practices (Carbon Trust, Ukie, UNEP's Playing for the Planet), product efficiency (consoles, engines, and less demanding designs), and cultural mobilisation (campaigns integrated into games with hundreds of millions of players). The degree of net material savings derived from the third avenue is difficult to quantify and remains outside the scope of this study.
5. Social Media
Social media is the most difficult market to measure. Its footprint is distributed across smartphones, fixed and mobile access networks, recommendation systems, storage, and data centres—and the majority of that infrastructure is shared with other digital uses. Even so, a reasonable order of magnitude can be established.
DataReportal places the social universe in 2025 at 5.24 billion active identities, equivalent to 63.9% of the global population, with an average usage of 2 hours and 21 minutes per day. The digital consumption analysis published in Nature Communications uses a global average user with 894 hours/year of social media and an average traffic of 0.31 GB/h, within a complete digital basket that emits 229 kgCO₂e/year per average internet user. The study itself indicates that, excluding video, each non-video category contributes approximately between 10% and 18% of the total. By assigning social media a band of 12-18% of those 229 kg, the aggregate 2025 footprint stands at 144 to 216 MtCO₂e; converted via a global network proxy, this is equivalent to 325 to 490 TWh of electricity, and the modelled indirect water usage stands at 490 to 1,720 billion litres.
Here, scale overcomes intensity. Usage per person does not require the raw computation of AI or the continuous power of high-performance gaming, but it aggregates many hours, almost always on smartphones, and mobilises networks and algorithmic recommendation on a planetary scale. The Nature Communications study itself highlights that social media is accessed via smartphone approximately 83% of the time by its archetypal user. The sustainability of the sector depends far more on terminal lifespan, network efficiency, compression, autoplay, and feed design than on the data centre in the strict sense.
The e-waste attributable exclusively to social media in 2025 remains, once again, unspecified. The primary identifiable vector is the smartphone: IDC projects between 1.25 and 1.26 billion smartphones shipped in 2025. These devices serve many functions, yet frequent phone renewal is the primary channel through which social media exerts material pressure and waste. The exact figure attributable requires a partitioning effort that does not currently exist in primary literature.
The positive side of social media for sustainability appears primarily as operational mitigation, not as a demonstrated net climate benefit for the market as a whole. The case of Meta is illustrative. In 2024, it declared 18.42 TWh of total electricity consumption—18.06 TWh in data centres—, 100% electricity matching with renewable attributes, a PUE of 1.08, a WUE of 0.19, and more than 1.6 billion gallons restored through water projects. However, the same report shows that, even with those renewable purchases, the location-based emissions of its data centres remained at 5.86 MtCO₂e and water extraction reached 4.145 billion litres. The sector can improve significantly, but its footprint remains material and cannot be rendered invisible through contractual metrics.
6. Quantitative Comparison
| Market | Electricity 2025 | Water 2025 | CO₂e 2025 | Confidence |
|---|---|---|---|---|
| AI | 82–202 TWh | 312.5–764.6 billion L | 32.6–79.7 MtCO₂e | Medium-high |
| Video game | 110–190 TWh | 170–670 billion L | 48–84 MtCO₂e | Low-medium |
| Social media | 325–490 TWh | 490–1,720 billion L | 144–216 MtCO₂e | Medium-low |
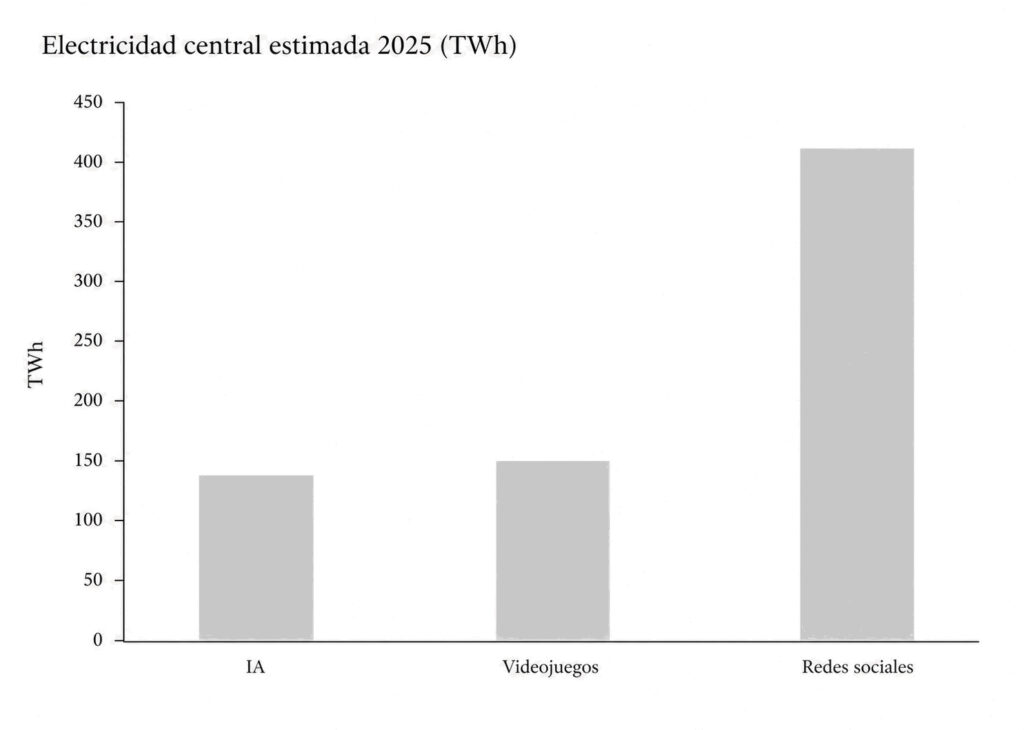
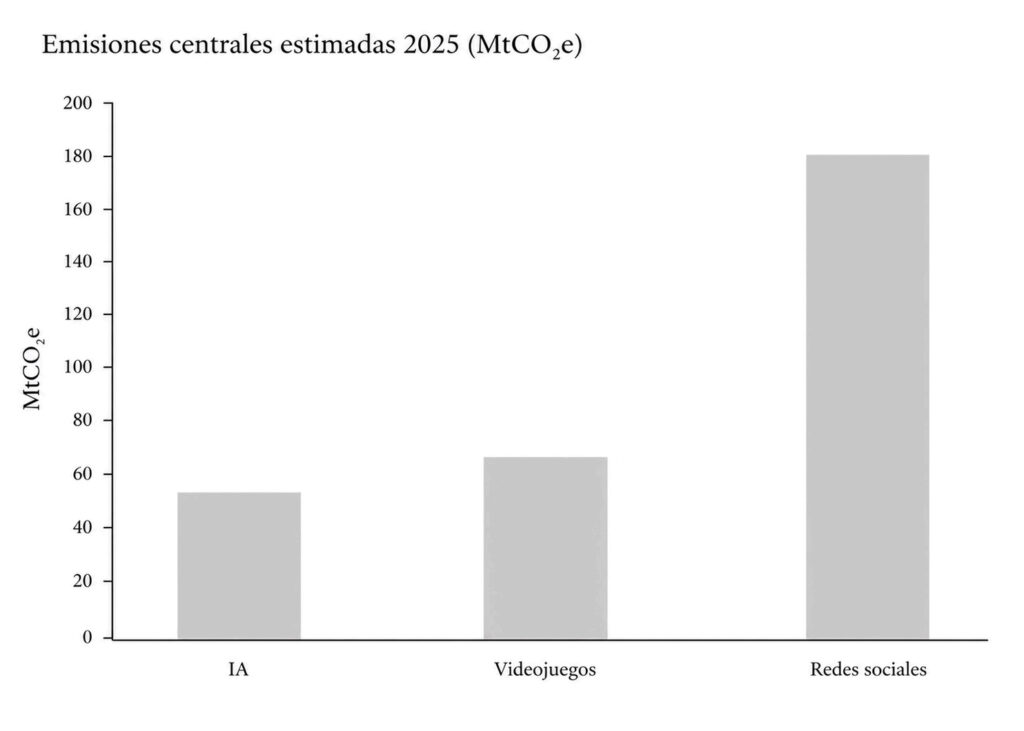
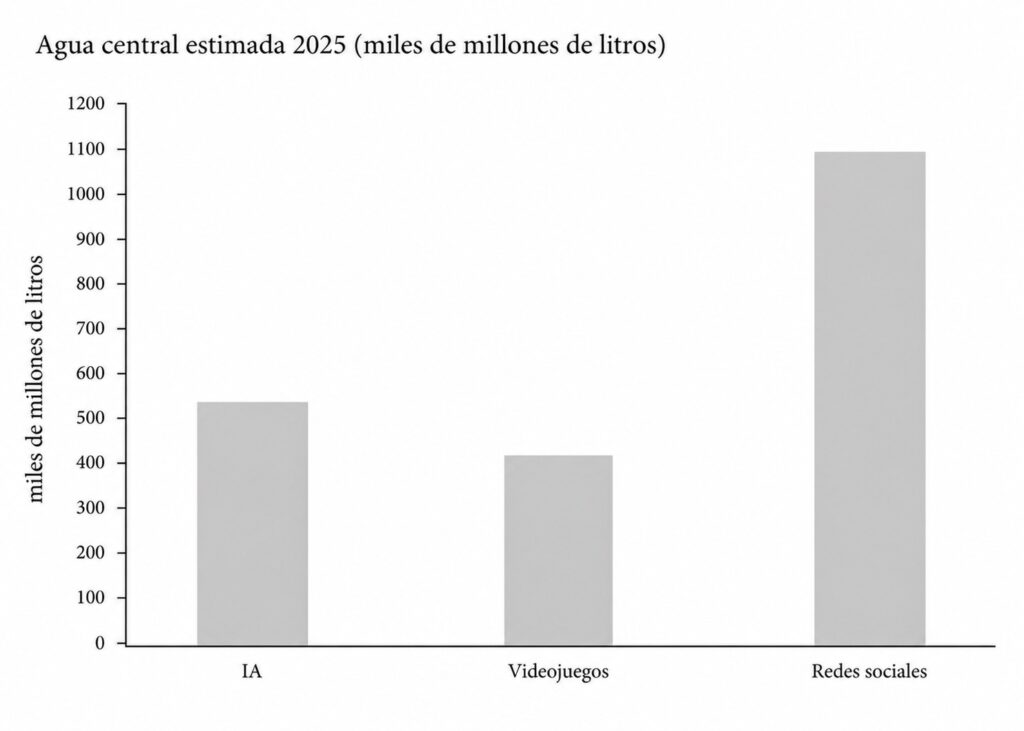
The charts should not be read as a 'league table' between the three markets. They are a structural comparison in which each figure carries its own level of confidence and its own system boundary. The reason social media appears so high is the massive scale of users and hours. The reason AI appears very high in intensity but not always above social media in aggregate is that it remains a less ubiquitous market, albeit much more intensive per unit of compute.
Looking only at the aggregate and declaring social media 'the worst market for sustainability' is a conclusion that the available evidence does not support as a robust assertion. What it does support is that social media most likely has the largest aggregate annual footprint of the three, with a medium-low confidence level, and that three distinct orders of magnitude coexist within the same digital ecosystem without public policy having yet articulated a proportional response.
7. The intensity/scale asymmetry as an ethical problem
Public discourse tends to treat the three markets as three species of the same genus: 'digital consumption'. The figures in the previous sections show that this is an error. It is not just that the magnitudes differ. It is that the structure of consumption is ontologically distinct in each one.
AI is, for now, an elective consumer market. Intensive use is concentrated among professional minorities, corporate deployments, and users with disposable income or technical curiosity. Anyone wishing to generate a thousand images with a diffusion model makes that decision consciously and separably. The footprint per user is very high, but the number of intensive users is still limited. This will likely change in the coming years, but today AI admits voluntary usage policies without grave social cost.
Social media is a structural consumer market. It is not merely that many people use networks: participation is encoded into the basic functioning of the contemporary economy, public administration, affective mediation, and family support networks. Public administrations communicate via X. Companies select candidates via LinkedIn. Families coordinate via WhatsApp and Facebook groups. Liberal professionals acquire clients via Instagram. The vast majority of the 5.24 billion users cannot opt out without paying a disproportionate social, professional, affective, or administrative cost.
Video gaming is in between. It is partially elective—no one is obliged to play—but it is also culturally normalised and widely integrated into the social lives of several generations. Its average use per person is significant, though not comparable to that of social media.
This distinction has serious ethical consequences. The question “what is ethical digital consumption?” means different things depending on the market structure. One cannot ask an individual user to reduce their social media consumption in the same vein as one asks them to reduce their meat consumption, air travel, or use of generative AI to create memes. Participation in social media is not an elective consumption in the sense that a Stable Diffusion session or a game of Cyberpunk 2077 is.
This does not exempt the user from any judgement, but it shifts the focus of the judgement. The question ceases to be 'what do you consume?' and becomes 'under what conditions is the consumption offered and who decides those conditions?'
8. Ethical consumption in structural markets
The distinction between an elective market and a structural market has consequences for the dominant ethical discourse on digital sustainability, which tends to moralise the individual user. In AI, where consumption is relatively elective, the question 'should you generate images with AI just for amusement?' is meaningful. In social media, where consumption is structural, the analogous question ('should you use social networks?') is hollow: the majority cannot stop doing so without paying a disproportionate cost.
This does not mean the user lacks agency. Real individual levers are concentrated in four points:
- Extending the service life of the smartphone, which is the primary material vector of social media.
- Limiting autoplay, background video, and default notifications.
- Choosing Wi-Fi over mobile data when possible, due to the difference in energy efficiency between networks.
- Reducing the consumption of non-essential video.
These levers are real but marginal compared to the structural levers, which lie in product design. If the feed is served with autoplay activated by default and the user must opt-out, the aggregate behaviour will be high-intensity video traffic. If smartphones are designed for 18–24 month lifecycles with increasing difficulty in replacing batteries and repairing screens, the aggregate will be smartphones renewed every 18–24 months. If the default quality of uploaded video is 1080p or 4K regardless of context, the aggregate will be high-quality video traffic even when the user’s screen does not benefit from it.
The ethics of digital consumption cannot be framed as an individual matter without falling into what the philosopher Hans Jonas termed a misapplied 'principle of responsibility': burdening the individual with the accountability for a system whose design they do not control. The moral burden is not symmetrical between users, product designers, platforms, and regulators.
9. Infrastructural responsibility
This is not an argument in favour of absolving the user and demonising platforms. It is an analytical clarification: in structural and mass consumer markets, the decisive lever lies in the infrastructure. And that infrastructure has identifiable parties responsible at three levels.
Product design. Those who define the defaults define the aggregate behaviour. Autoplay, default video quality, frequency of forced updates, the hardware's planned obsolescence cycle, and notification defaults. These decisions are made within product teams whose metrics are engagement, retention, and conversion, not environmental impact.
Business model. When the business is attention and that attention is monetised through exposure to advertisements, the structural incentive pushes towards more time, more video, more traffic, and more hardware renewal. The environmental footprint is an externality not accounted for in the balance sheets of most dominant platforms. As long as this remains unchanged, marginal improvements in technical efficiency—a lower PUE, more efficient compression—will be offset and surpassed by the growth in usage.
Regulatory frameworks. These are the points where collective ethics can operate with a real, aggregate effect:
- Mandatory disclosure standards for energy, water, PUE, WUE, and emissions per AI workload, not merely at an aggregate corporate level.
- Minimum requirements for the repairability and service life of smartphones, in line with what the European Right to Repair Directive is beginning to articulate.
- Restrictions on the deployment of data centres in basins with documented water stress.
- Obligation for additional renewable capacity—not merely contractual matching—associated with the growth of data centre loads.
- Regulation of aggressive autoplay and notification defaults, in line with the initial proposals already circulating regarding 'design defaults' in the sphere of digital mental health and attention.
- Penalisation of the deployment of AI with low social value when the energy and water costs are disproportionate.
For video games, the four most effective levers are matters of public governance: extending hardware service life through mandatory repairability, expanding GCVA-type standards to further markets, incorporating energy consumption metrics into toolchains and publishing certifications, and mandating low-power modes that are active by default. This is the sector with the greatest scope for immediate technical improvements at the lowest social cost.
Digital sustainability will not be resolved by the sum of better individual choices. It will be resolved—if it is resolved at all—through infrastructural interventions at the three levels mentioned above.
10. Limitations of the study
The main limitation is sectoral transparency. For AI, specific 2025 studies already exist, but granular disclosure by company and workload remains lacking. For video games and social media, the problem is greater: there is no global, audited, and homogeneous account of the 2025 market that clearly separates hardware, software, networks, and end-use. In these two markets, the figures in this study should be read as plausible ranges, not as official inventories.
The system boundary between markets is asymmetrical. AI is reasonably measured as an operational compute footprint. Video games and social media are ecosystems of mass digital consumption where the user terminal carries significant weight. Absolute comparability between rows is not perfect.
The e-waste attributable to each market in 2025 remains largely unspecified in primary evidence. The figures provided in this study for 2025 are aggregated and approximate, not audited.
This study maintains that these limitations do not invalidate the primary argument—the asymmetry of intensity versus scale and infrastructural responsibility—because that argument operates on structures of consumption rather than exact figures. What the figures establish is the relative order of magnitude. What the ethical argument demands does not follow from a tenth of a percentage point more or less within a confidence interval, but from the qualitative fact that three distinct orders of magnitude coexist within the same ecosystem with three distinct structures of consumption.
11. Conclusion
Three conclusions are derived from the analysis.
The first is descriptive. AI has the highest intensity per unit of use and, currently, a significant aggregate footprint that remains below that of social media. Social media most likely has the highest annual aggregate footprint and the lowest demonstrated potential for net savings within its own market. Video games fall in the middle, with the most technically addressable footprint and the most mature sectoral standards.
The second is methodological. The question 'which of the three is the worst?' is poorly framed. Each market has a distinct structure of consumption—elective in AI, structural in social media, intermediate in video games—and demands distinct ethical responses. Treating the three as moral equivalents leads to false consensus, the empty moralisation of the user, and public policies that blame the weakest side of the equation.
The third is ethical. Responsibility for digital sustainability in 2025 is not an individual matter. It is a matter of product design, business model, and regulation. Individual levers exist, but they are marginal compared to the decisions made by those who design, finance, and regulate these infrastructures. While public debate remains focused on whether the user should use ChatGPT less, the decisions that truly move the needle—hardware lifecycles, product defaults, data centre location, regulation of attention-based business models—continue to be made far from public scrutiny.
Author's position
This study is not presented as a neutral exercise. The signatory works professionally with digital technologies: they employ video games and artificial intelligence as tools in their experimental practice of artistic and social processes, register works on the blockchain when the nature of the work requires it, distribute on decentralised networks, and are an active user of the social networks identified here as the market with the largest aggregate footprint. This position does not place me outside the described problem. It places me within it.
The ethical position consistent with the analysed data is not technological abstinence—which would be ineffective and individually costly—nor is it uncritical adoption. It is to demand radical transparency, common standards for measurement and reduction, and responsible infrastructural design from those who possess the power and the data to produce them. The public conversation on digital sustainability has spent too much time blaming the user for consuming and too little time asking why the system is designed so that such consumption is inevitable, opaque, and difficult to measure.
Sources
[1] International Energy Agency (IEA). Energy and AI, 2025. https://www.iea.org/reports/energy-and-ai
[2] International Energy Agency (IEA). Energy demand from AI, 2025. https://www.iea.org/reports/energy-and-ai/energy-demand-from-ai
[3] Patterns (Cell Press). 'The carbon and water footprints of data centres and what this could mean for artificial intelligence', 2025. https://www.sciencedirect.com/science/article/pii/S2666389925002788
[4] Nature Sustainability, 'Environmental footprint of AI servers', 2025. https://www.nature.com/articles/s41893-025-01681-y
[5] Nature Computational Science. 'E-waste from generative AI', 2024. https://www.nature.com/articles/s43588-024-00712-6
[6] Mills, E. & Mills, N., Lawrence Berkeley National Laboratory. 'Taming the energy use of gaming computers', Energy Efficiency / Computer Games Journal, 2019. https://link.springer.com/article/10.1007/s40869-019-00084-2
[7] Microsoft. Global platform baselines for Xbox, 2024. https://learn.microsoft.com/en-us/gaming/sustainability/global-platform-baselines
[8] Game Console Voluntary Agreement (GCVA). 2023 Review Report. https://efficientgaming.info/wp-content/uploads/documents/Agreements/2023_GCVA_Review_Report_FINAL.pdf
[9] UNEP / Playing for the Planet. Annual Impact Report 2024. https://www.unep.org/resources/report/playing-planet-annual-impact-report-2024
[10] DataReportal. Digital 2025: Global Overview Report. https://datareportal.com/reports/digital-2025-global-overview-report
[11] Nature Communications. 'The environmental footprint of digital consumption', 2024. https://www.nature.com/articles/s41467-024-47621-w
[12] GreenIT.fr. World Study 2025: Environmental impacts of digital technology worldwide. https://greenit.eco/wp-content/uploads/2025/05/greenit-world-study-2025-20250417.pdf
[13] IDC. Worldwide Smartphone Tracker, 2025. https://my.idc.com/getdoc.jsp?containerId=prUS53965725
[14] Meta. 2025 Sustainability Environmental Data Index (2024 data). https://sustainability.atmeta.com/wp-content/uploads/2025/10/Meta_2025-Environmental-Data-Index.pdf
[15] IEA. AI is set to drive surging electricity demand from data centres, 2025. https://www.iea.org/news/ai-is-set-to-drive-surging-electricity-demand-from-data-centres-while-offering-the-potential-to-transform-how-the-energy-sector-works
Update note
A more concise journalistic version of this study, adapted for a general audience, was published in eldiario.es under the title The problem of ethical digital consumption extends beyond AI. Available at: https://www.eldiario.es/opinionsocios/problema-consumo-digital-etico-ia_132_13232659.html
Series · Infrastructures
This piece forms part of a six-part series examining the influence of digital and cultural systems upon art. The overarching thesis posits that within contemporary systems, the decisive factor is not individual conduct but rather infrastructural design. The series commences with the capture mechanisms of these systems and concludes with their exclusionary practices.